Tag: startup pitch strategy

  • Sweat Equity: What It Means for Startup Founders
    Sweat Equity: What It Means for Startup Founders

    Sweat Equity: What It Means for Startup Founders

    James Church

    WRITEN BY

    James Church

    Author, Investable Entrepreneur

    James is an award-winning business advisor and best-selling author. His clients have raised over £200m in early-stage funding. 

    Sweat equity is the share of a company someone earns through work rather than cash. Early teams use it constantly, because the bank balance rarely matches the ambition. So instead of paying a salary, the business hands over ownership. 

    sweat equity means shares granted in return for time, skill and effort. Founders, early hires and advisers all receive it. Value it against market rates, put it on paper, and attach vesting to every grant. 

    The idea sounds simple, yet it causes more founder disputes than almost anything else. This guide explains the sweat equity meaning in plain terms, then shows how to price it, protect it and explain it to investors. 

    What Is Sweat Equity? 

    Sweat equity is ownership earned through contribution instead of cash. A designer builds your brand for free and receives two percent. A technical partner writes the first product and takes twenty percent. Both examples describe the same thing. 

    Some people call it sweat capital, and the meaning does not change. The contributor gives time and skill, while the company gives a stake in future value. 

    Cash investment works differently. An investor wires money, so the value arrives immediately and everyone can measure it. Sweat equity arrives slowly, and that is exactly why it needs clear rules. 

    Why Sweat Equity Matters at the Early Stage 

    Most startups begin with almost no money. Founders still need designers, developers, marketers and advisers, however, so something has to fill the gap. 

    Sweat equity fills it in three useful ways: 

    • It preserves cash. Every pound saved extends your runway. 
    • It creates commitment. Owners behave differently from contractors. 
    • It attracts senior help. Experienced people will trade time for upside. 
    • It proves momentum. Investors like teams who build before funding arrives. 

    There is a catch, though. Equity is the most expensive currency you own, since you can only give it away once. 

    Sweat Equity Meaning in Practice: How to Value It 

    Guessing is where founders go wrong. Use a simple, repeatable method instead. 

    Start With a Market Rate 

    Ask what the work would cost if you paid for it. A senior developer might charge £600 per day, while a part-time marketer might charge £350. Write those numbers down. 

    Track the Hours Properly 

    Keep a shared log from day one. Record dates, tasks and hours, because memory fades and disagreements grow. A simple spreadsheet works perfectly well. 

    Convert the Value Into Shares 

    Multiply the hours by the day rate to get a cash value. Then divide that figure by your current company valuation. If someone contributes £30,000 of work and the business is worth £1m, they have earned roughly three percent. 

    Apply a risk multiplier if you want to reward early belief. Many teams use 1.5x or 2x for work done before any funding. Our guide on how to value a company walks through the valuation side in more detail. 

    Sweat Equity or Cash: Which Should You Use? 

    Both have a place, so the answer depends on the role. 

    Use equity for long-term contributors who shape the business. Use cash for short, defined jobs such as a logo or a landing page. Mixing the two also works well, and a reduced fee plus a small grant often keeps everyone happy. 

    Ask one question before every grant: will this person still matter in three years? If the answer is no, pay them instead. 

    Vesting: The Rule That Protects Everyone 

    Never hand over shares on day one. Use vesting, which releases equity gradually over time. 

    The standard UK structure runs for four years with a one-year cliff. Nothing vests in the first twelve months. After that, shares release monthly until the term ends. 

    Set the terms before anyone starts work, because renegotiating later damages trust quickly. A short written agreement takes an afternoon, while an unresolved equity argument can take a year. 

    Vesting protects the company when someone leaves early. Equally, it protects the contributor, because their stake keeps building as they deliver. Add good leaver and bad leaver clauses too, and get a solicitor to draft the paperwork. 

    What Investors Check About Sweat Equity 

    Investors rarely object to sweat equity itself. They do object to a messy cap table. 

    Expect these questions during due diligence: 

    1. Who owns what today, and on what terms?
    2. Is every grant documented and signed? 
    3. Does vesting apply to the founders as well? 
    4. Are any past contributors still holding dormant shares? 
    5. Has anyone promised equity without a written agreement? 

    Verbal promises are the biggest red flag. A single unresolved claim can delay a round by months, so tidy the paperwork before you pitch. If you are unsure where you stand, read is your startup ready to raise investment. 

    Common Sweat Equity Mistakes 

    The first mistake is giving away too much, too soon. Ten percent feels cheap when the company is worth nothing, yet it feels painful at Series A. 

    The second mistake is skipping documentation. A conversation is not an agreement, and email trails rarely survive a dispute. 

    The third mistake is ignoring performance. Tie grants to milestones where you can, so effort and reward stay connected. 

    The fourth mistake is forgetting future rounds. Investors will want an option pool of ten to fifteen percent, and that pool usually dilutes the founders alone. 

    Tax and Legal Points to Check 

    Shares given for work can create a tax charge, and the rules vary by structure and timing. UK companies often use share option schemes rather than direct grants for that reason. The government’s guidance on employee share schemes explains the main options. 

    Always speak to an accountant and a solicitor before issuing shares. This article is general information, not tax or legal advice, and the cost of getting it right is far lower than the cost of fixing it later. 

    Sweat Equity FAQ 

    What is sweat equity in simple terms? 

    It is ownership earned through work instead of money. Someone contributes time and skill, then receives shares in return. 

    How much sweat equity should a co-founder get? 

    There is no fixed answer. Consider the role, the hours, the risk taken and the stage of the business, then apply vesting. 

    Is sweat equity taxable in the UK? 

    It can be. Shares issued for services may count as employment income, so take professional advice first. 

    Can sweat equity be taken back? 

    Only if your agreement allows it. Vesting and leaver clauses are the standard protection. 

    Do investors count sweat equity as investment? 

    Not as cash. They do count it as evidence of commitment, which matters during a pitch. 

    What is the difference between sweat equity and sweat capital? 

    Nothing meaningful. Both describe value created through effort rather than money. 

    The Bottom Line 

    Sweat equity turns effort into ownership, and that trade builds most early startups. Value it honestly, document every grant, and attach vesting without exception. Do that, and your cap table will support your next raise instead of blocking it. 

    Want investors to understand your story quickly? Explore our pitch deck consulting or join the free investor workshop. 

    About the Author

    James Church is an award-winning UK startup advisor, fundraising strategist, and author of Investable Entrepreneur. He has helped founders raise more than £200 million in investment by improving investor readiness, refining fundraising strategies, and developing compelling pitch decks.

    Through Investable Entrepreneur, James works with entrepreneurs to create investor presentations that communicate value clearly, strengthen fundraising confidence, and improve investment outcomes through practical, real-world expertise.
  • How to build a pitch that intrigues investors

    How to build a pitch that intrigues investors

    How to build a pitch that intrigues investors

    James Church

    WRITEN BY

    James Church

    Author, Investable Entrepreneur

    James is an award-winning business advisor and best-selling author. His clients have raised over £200m in early-stage funding. 

    Founders often approach an investment pitch as though its job is to explain the whole company. They take the business plan, remove some of the detail, put the remaining information into 15 or 20 slides and assume the result is an investor pitch.

    That misunderstands the job of the document. Your pitch isn’t supposed to answer every question an investor could eventually ask about the company.

    Its first job is to make the opportunity understandable and interesting enough for the investor to want the next conversation. The deeper analysis can come later through meetings, your investment memo, financial model, data room and due diligence.

    Think of the pitch as the start of the conversation

    An early-stage investor is being asked to exchange capital for equity in a company where much of the value still sits in the future. They’re evaluating what exists today, but they’re also considering what the business could become and whether they believe you can get it there.

    That means your pitch has to do more than describe the company. It needs to articulate the idea, demonstrate the commercial opportunity, establish credibility and make the future worth investigating.

    Trying to provide strategic depth on every part of the business can work against that aim. Investors have finite attention, and every piece of information you include competes with the information that actually moves the argument forward.

    The question I’d ask isn’t, “What else could we tell them?” It’s, “What does an investor need to understand and believe before they’ll want to continue?”

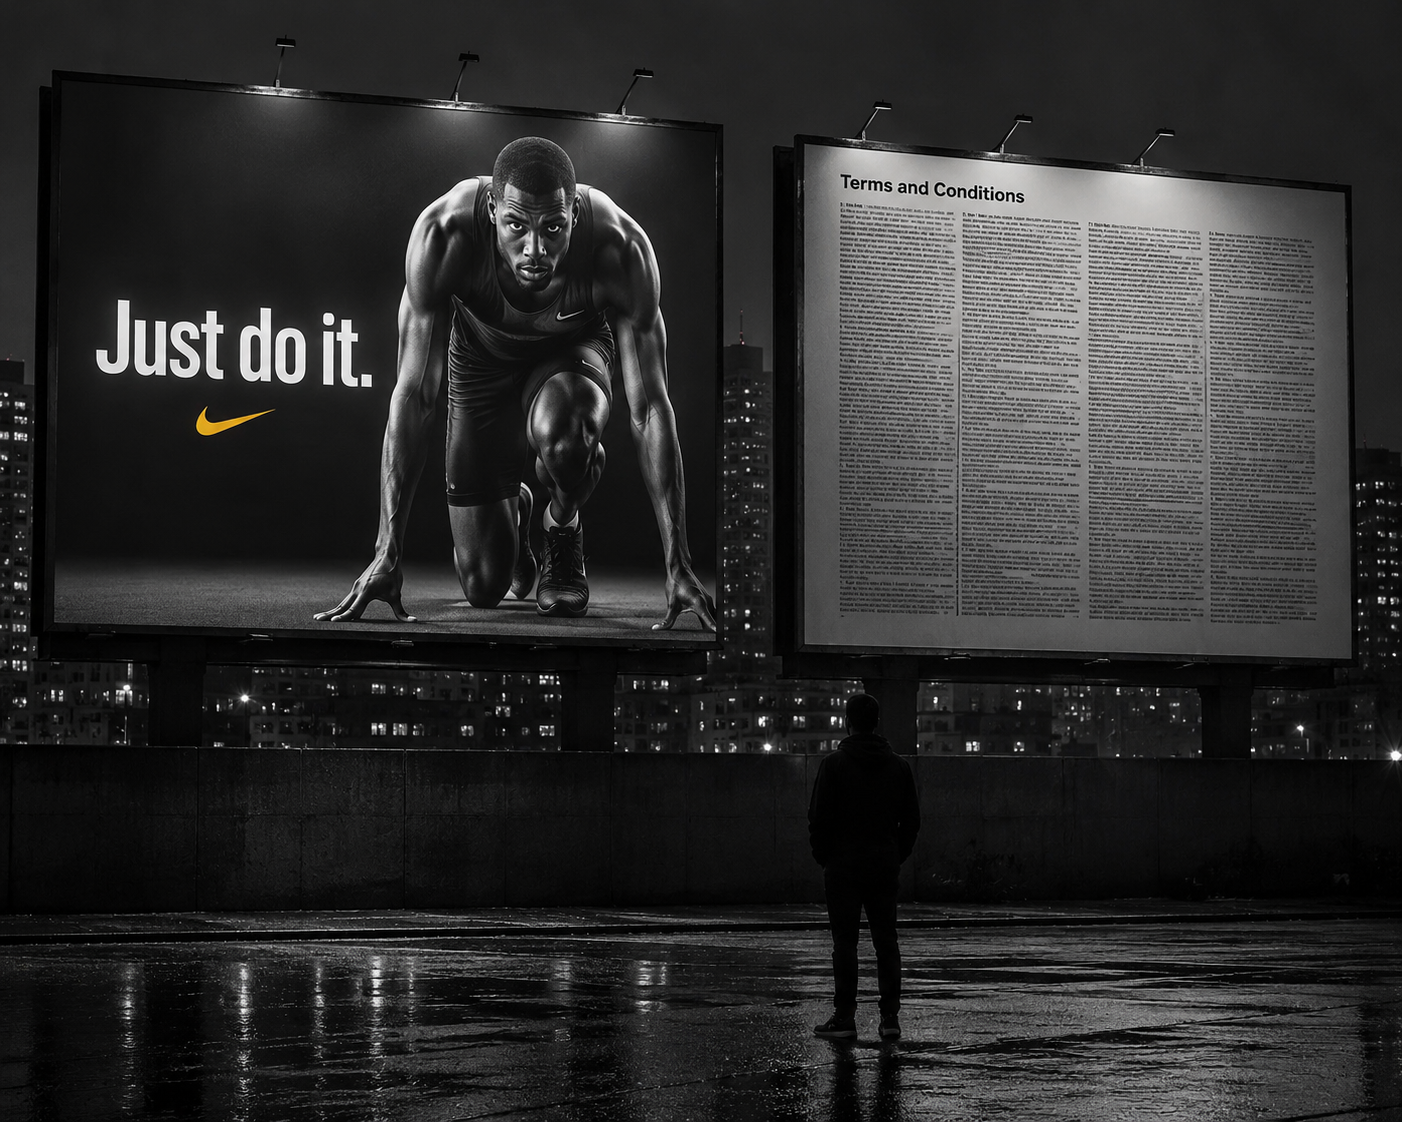
    Think of your pitch like a billboard. You might buy a pair of Nike trainers because of the simple and engaging story they tell through a short headline and an engaging image. However, if they were to replace that with the manufacturing specifications, there’s very little chance you would engage with their product.

    Start thinking before you start designing

    I developed the Six Principles of the Perfect Pitch because I kept seeing founders start with the final output. They thought they needed a deck, so they opened presentation software, copied a familiar slide structure or asked an AI tool to generate one.

    That approach can create something that looks plausible while skipping the harder work that comes first. A convincing investment pitch starts with the investment case and moves towards the presentation rather than beginning with the presentation and hoping the investment case emerges.

    The six principles are Plan, Projections, Structure, Content, Clarity and Design. The order is deliberate because every stage gives the next one something stronger to work with.

    1. Plan the investment case

    Before thinking about slides, work out what you’re actually asking someone to back. What opportunity exists, what makes the company capable of pursuing it, why does investment make sense now, and what could happen if the plan succeeds?

    This is also where you need to challenge the assumptions behind the story. A beautifully written claim about a huge market doesn’t help if the logic underneath it is weak.

    Planning forces you to confront those gaps before presentation work disguises them. It gives the pitch a commercial argument and builds credibility in you as a founder.

    2. Build credible projections

    Financial projections aren’t there because investors expect to see a spreadsheet containing increasingly large numbers. They need to help the investor understand the economics of the opportunity.

    Your assumptions should connect to the story you’re telling about customers, pricing, growth, cost and capital. If the narrative describes one business model while the model describes another, investors will notice the disconnect.

    At an early stage, nobody expects you to predict the future perfectly. They do expect the numbers to show that you understand the commercial model you’re trying to build and have thought through what needs to happen for the company to grow.

    3. Structure the argument

    Once you know what you’re trying to communicate, decide the order in which the investor needs to encounter it. Good individual slides can still produce a poor pitch when the argument jumps around or makes the reader do the work of connecting everything together.

    Structure should create logical progression. Each section needs to give the investor enough context to understand what comes next, moving them from the opportunity through the evidence and towards the future you’re asking them to believe in.

    That doesn’t mean every pitch must follow one universal slide order. Different businesses need different emphasis, so structure should follow the investment argument rather than a generic template.

    4. Choose the content that earns its place

    This is where many decks start to fail. The founder knows the company in extraordinary depth, which means almost everything feels relevant.

    The investor has a different problem. They’re trying to decide whether this opportunity deserves more of their time, so the pitch needs to prioritise the information that helps them make that decision.

    More information can reduce comprehension because the important argument becomes buried inside detail. Technical specifications, secondary features or background analysis may be valuable later without deserving prime space in the pitch.

    Good editing is therefore part of good pitching. Removing something isn’t evidence that the subject doesn’t matter; it just means you’ve decided it doesn’t need to be understood yet.

    5. Make the proposition clear

    Clarity is where the investment case becomes accessible to another person. A founder can understand every part of the company and still struggle to communicate it because they’ve spent so long inside the business that important assumptions now feel obvious.

    One useful exercise is to take the deck away completely. Explain in a few clear sentences what the company does, why it matters, where it could go and why an investor should care.

    Avoid jargon and resist the urge to give a ten-minute answer. If the proposition becomes harder to understand without the slides, keep working on the proposition before polishing the deck.

    This is also a useful test of AI-generated language. A model can make a sentence sound sophisticated while making the message harder to understand, and founders can end up presenting words they would never naturally use themselves.

    6. Use design to support communication

    Only now do we arrive at design. Good presentation design matters because investors need to consume the information easily, understand hierarchy and know where to focus their attention.

    What design can’t do is create a compelling investment case where none exists. A polished deck with weak logic remains a weak pitch, although it may take slightly longer for the weakness to become obvious.

    Design should enhance the argument rather than become the argument. When the thinking is strong, a great presentation helps investors access it more quickly.

    Build for the next conversation

    A successful investment pitch doesn’t need to complete due diligence in 20 slides. It needs to give the investor a clear enough view of the opportunity to decide that further investigation is worth their time.

    That changes the way you write your deck. Instead of judging the pitch by how much of the company it contains, judge it by whether an intelligent investor can understand the opportunity, see enough evidence to take it seriously and become curious about what happens next.

    It also changes how you use the tools at your disposal. AI can help you explore wording, challenge assumptions and improve drafts, but it shouldn’t be asked to replace the commercial thinking that makes your company different from every other startup using the same technology. Nor should it replace your natural language.

    After all, investors are investing in founders, not prompts. They’re considering whether to back your company, your plan and your ability to execute it.

    If you understand the business but need help turning that understanding into an investment pitch that creates clarity, credibility and investor interest, my free workshop, How to Make Investors Love You, is the natural next step. It covers the strategies and tactics my founders are implementing right now to gain huge amounts of interest from active investors.

    About the Author

    James Church is an award-winning UK startup advisor, fundraising strategist, and author of Investable Entrepreneur. He has helped founders raise more than £200 million in investment by improving investor readiness, refining fundraising strategies, and developing compelling pitch decks.

    Through Investable Entrepreneur, James works with entrepreneurs to create investor presentations that communicate value clearly, strengthen fundraising confidence, and improve investment outcomes through practical, real-world expertise.
  • Why starting your fundraising too early can cost you investor opportunities

    Why starting your fundraising too early can cost you investor opportunities

    Why starting your fundraising too early can cost you investor opportunities

    James Church

    WRITEN BY

    James Church

    Author, Investable Entrepreneur

    James is an award-winning business advisor and best-selling author. His clients have raised over £200m in early-stage funding. 

    If you’re preparing to raise investment, it’s tempting to start talking to investors as soon as the pitch deck looks reasonably good. Fundraising takes time, cash may already be getting tight, and every week spent preparing can feel like another week that you could have been building your pipeline.

    That urgency creates one of the most expensive mistakes in fundraising – launching before the investment proposition is ready. The deck is “good enough”, the numbers are nearly finished, and the story makes sense as long as you’re there to explain it.

    The problem is that your first investor conversations aren’t a rehearsal. They’re genuine opportunities with people you may find difficult to approach again once they’ve decided the business isn’t for them.

    The danger in using investors as your quality-control process

    There will always be things you learn once you enter the market. Investors will ask questions you didn’t expect, different types of investors will care about different issues, and no amount of preparation can simulate every conversation.

    That doesn’t mean you should use investors to discover weaknesses that could have been found beforehand. If your projections fall apart under basic scrutiny, your investment story is confusing or your supporting information isn’t ready, you’re learning an expensive lesson in front of a valuable prospect.

    Early rejection can also change the way you behave. After several unsuccessful meetings, founders often start adjusting the story after every conversation, adding new slides or trying to anticipate every possible objection.

    The pitch becomes less consistent at exactly the point when you need more conviction in it. Instead of entering meetings knowing the argument has been thought through, you start just hoping the next version lands better.

    Instead, preparation should remove as many avoidable weaknesses as possible before you approach the market. Then genuine investor feedback can help you refine a strong proposition rather than construct one from scratch.

    What being ready actually means

    Fundraising readiness is much broader than creating a pitch deck. You need to understand what you’re raising, why you’re raising it, what investment case you’re asking someone to believe and how you’ll support that case as an investor moves through the process.

    You also need a sensible view of who should receive the opportunity. A brilliant pitch sent to investors whose stage, sector, cheque size or mandate doesn’t fit your company is still unlikely to get you very far.

    I suggest working through six stages before launching an investment campaign:

    Step 1: Define the raise

    Start with the transaction rather than the presentation. Be clear about how much capital you need, why you need it now, what that capital allows the company to achieve and what type of investor could reasonably participate.

    Those questions affect almost everything that follows. A founder raising £250,000 from angels has a different fundraising task from one seeking several million pounds of institutional venture capital, even if the underlying company is the same.

    You should also be able to connect the amount you’re raising to progress in the business. Investors aren’t only being asked to fund expenditure. They want to understand what their capital helps the company become.

    Step 2: Work on the investment story

    An investor needs to understand the business that exists today and the opportunity you’re trying to build tomorrow. Your investment story connects those two things.

    That means explaining the problem or opportunity, why the company needs to exist, what gives you a credible position and where the business could go if the plan works. It also means deciding what you want an investor to believe before you start worrying about individual slides.

    Founders often know these things instinctively but have never turned them into a coherent argument. This becomes obvious when someone outside the business tries to understand the opportunity without the founder filling in the missing pieces.

    Step 3: Build the pitch

    Once the investment story is clear, you can build the pitch around it. Work through the business case and projections first, then decide the structure, content, wording and design that best communicate the argument.

    The order you tackle this matters. Starting with slide layouts encourages you to think about what a pitch should look like before you’ve established what the investor actually needs to understand.

    A useful test is to ask whether the pitch can stand without your commentary. Could someone unfamiliar with the business explain what you do, why the opportunity is interesting and what you’re asking an investor to back after reading it?

    If the answer is no, the pitch needs work before you launch.

    Step 4: Prepare the supporting assets

    A successful pitch creates another problem: the investor wants to know more. You need to be ready for that.

    Depending on the stage and nature of the raise, the next step might involve an investment memo, financial model, data room and supporting evidence. The exact materials will vary, but the principle stays the same – don’t create interest and then make the investor wait while you build the information needed to continue.

    That delay can drain momentum from a conversation. It will also demonstrate that you’re not properly prepared.

    Step 5: Identify the right capital

    Only once the proposition and supporting assets are taking shape would I spend serious time building the investor pipeline. Start with relevance rather than volume.

    Look at investment stage, sector, geography, cheque size, portfolio, investment thesis and any other factor that determines whether your company fits what an investor actually backs. There’s little value in building a list of hundreds of names if most of them were unlikely to invest in the first place.

    This also improves the quality of your outreach. When you understand why an investor may be relevant, you can approach them with a reason rather than treating fundraising as a mail-merge exercise.

    Step 6: Launch the campaign

    Now outreach makes sense because the machine behind it is ready. You know what you’re selling, you’ve worked through the argument, your materials support it and you’ve identified the investors most likely to care.

    That doesn’t guarantee a successful raise. No amount of preparation can make every company investable or persuade investors whose priorities don’t align with yours.

    What preparation does do is reduce avoidable failure. If an investor says no, you’re in a much better position to work out whether the objection is fundamental, investor-specific or something that genuinely needs changing.

    A final readiness check

    Before you launch, look at the proposition from the investor’s side. Can someone unfamiliar with the company understand what it does, why the problem matters, why the commercial opportunity is attractive and where the company could go?

    Then go deeper. Do the financial projections support the story, does the information appear in a logical order, is every important section earning its place, and are the supporting assets ready if someone wants to continue?

    Finally, make sure you know exactly what you’re raising and have identified investors for whom the opportunity is genuinely relevant. Those questions are more useful before outreach than after your first ten rejections.

    Fundraising will always contain uncertainty because you can’t control investor appetite, timing or the alternatives available to them. You can control how prepared you are when the opportunity to pitch appears.

    If you’re currently preparing a round and want to see where the gaps are before approaching investors, take the Investor Ready Scorecard. It will help you assess whether you’re genuinely ready to raise and identify areas that may weaken the campaign before you put it in front of the market.

    About the Author

    James Church is an award-winning UK startup advisor, fundraising strategist, and author of Investable Entrepreneur. He has helped founders raise more than £200 million in investment by improving investor readiness, refining fundraising strategies, and developing compelling pitch decks.

    Through Investable Entrepreneur, James works with entrepreneurs to create investor presentations that communicate value clearly, strengthen fundraising confidence, and improve investment outcomes through practical, real-world expertise.
  • Investor Pitch Deck Consultant: Pitching Guide

    Investor Pitch Deck Consultant: Pitching Guide

    Investor Pitch Deck Consultant: How to Pitch Investors

    James Church

    WRITEN BY

    James Church

    Author, Investable Entrepreneur

    James is an award-winning business advisor and best-selling author. His clients have raised over £200m in early-stage funding. 

    What does an investor pitch deck consultant do?

    A consultant helps founders organise their business story, explain the investment opportunity, and present information in a format investors can understand quickly. Working with an investor pitch deck consultant can improve the structure, messaging, evidence, financial presentation, and funding request while helping founders prepare for important investor questions.

    A pitch deck is not simply a collection of attractive slides. It is a fundraising document that explains why a business deserves investment and how the company plans to use that funding to grow.

    A strong investor presentation should explain:

    • The customer problem
    • The proposed solution
    • The target audience
    • The market opportunity
    • The business model
    • Existing traction
    • The growth strategy
    • Competitor positioning
    • The founding team
    • Financial projections
    • The funding request
    • Planned use of funds

    .
    Each slide should communicate one clear idea. Investors often review many opportunities, so they may lose interest if the presentation is confusing, repetitive, or filled with unnecessary detail.

    Professional support can help founders decide which information matters most. It can also identify weak claims, missing evidence, unrealistic financial assumptions, and unclear sections before the presentation reaches investors.

    How should founders prepare to pitch investors?

    Founders should prepare by understanding their audience, refining their investment story, gathering relevant evidence, and practising clear answers to likely questions. Learning how to pitch to investors involves more than reading slides aloud. Founders must explain why the problem matters, why their solution is credible, and how investment will support measurable growth.

    The presentation should begin with a specific problem. Founders should explain who experiences it, why it matters, and why existing solutions are not good enough.

    The solution should then show how the business addresses that problem. Avoid listing every product feature. Focus on the value customers receive and why the solution is better than available alternatives.

    Investors will also want evidence that customers care about the problem. Useful validation may include:

    1. Customer interviews
    2. Pilot programmes
    3. Product usage
    4. Early revenue
    5. Letters of intent
    6. Strategic partnerships
    7. Waiting lists
    8. Repeat purchases
    9. Customer retention
    10. Sales pipeline

    .
    The right evidence depends on the company’s stage. A pre-seed startup may rely on interviews and prototype testing, while a seed-stage company may be expected to show revenue, customer growth, or retention.

    The market section should be realistic. Large global figures can be useful, but they should not replace a clear explanation of the first customer segment and how the business plans to reach it.

    Founders should also explain the business model simply. Investors need to understand who pays, what they pay for, how much they pay, and how revenue can increase over time.

    What do UK investors expect from a startup pitch?

    UK investors generally expect a clear opportunity, credible evidence, realistic financial planning, a capable team, and a specific funding request. Founders preparing to pitch to investors uk should research the investor’s preferred sectors, funding stages, cheque sizes, portfolio companies, and investment criteria before making contact.

    Different investors have different expectations. Angel investors may focus heavily on the founder, market opportunity, and early potential. Venture capital firms may expect evidence that the business can scale rapidly and become significantly more valuable.

    Founders should tailor the presentation to the investor without changing the core business story. The deck should show why the opportunity matches that investor’s interests and experience.

    UK investors may ask questions about:

    • Customer acquisition
    • Revenue model
    • Market size
    • Competitor activity
    • Intellectual property
    • Regulatory requirements
    • Financial forecasts
    • Founder commitment
    • Hiring plans
    • Exit opportunities

    .
    The funding request should clearly state how much capital is being raised and what the company plans to achieve with it.

    For example, the investment may be used to:

    • Complete product development
    • Hire key team members
    • Expand sales activity
    • Test new markets
    • Improve customer acquisition
    • Meet regulatory requirements
    • Build operational capacity

    .
    Each spending area should connect to a measurable milestone. Investors want to know what will be different after the money has been spent.

    How can founders make their pitch more convincing?

    Founders can make their pitch more convincing by using evidence, simplifying the story, and presenting realistic assumptions. Strong presentations do not depend on exaggerated claims. They build confidence by showing that the founder understands the customer, market, risks, and route to growth.

    The traction slide should provide context. Instead of simply stating a user or revenue figure, explain how quickly it has grown, over what period, and why it matters.

    The competitor slide should also be honest. Claiming that the business has no competitors can damage credibility. Customers usually have another product, a manual process, or the option to do nothing.

    A useful competitor section explains:

    • Which alternatives customers currently use
    • How the startup is different
    • Why that difference matters
    • What may make the advantage sustainable

    .
    The team slide should connect experience to execution. Founders should explain why their skills, industry knowledge, customer relationships, or technical expertise make them suitable for building the company.

    Before approaching investors, founders should practise the presentation aloud. This helps identify unclear slides and prepares the team to answer questions confidently.

    The final deck should be concise, professional, and easy to follow. It should create enough interest for the investor to continue the conversation, request more information, or begin due diligence.

    Frequently Asked Questions

     What does an investor pitch deck consultant do?

    An investor pitch deck consultant helps founders create a clear, compelling pitch deck that communicates their business, market opportunity, traction, financials, and investment opportunity to potential investors.

    How many slides should an investor pitch deck contain?

    Most investor pitch decks contain around 10 to 15 core slides. The exact number matters less than having a clear story, relevant evidence, and a specific funding request.

    What makes an investor pitch deck effective?

    An effective deck clearly explains the problem, solution, market, business model, traction, team, financial plan, funding request, and use of funds.

    Should founders use the same pitch deck for every investor?

    The core story should remain consistent, but founders should adjust the presentation based on the investor’s sector interests, funding stage, investment criteria, and likely questions.

    About the Author

    James Church is an award-winning startup fundraising consultant and the Amazon best-selling author of Investable Entrepreneur. His clients have raised more than £200 million in startup funding. Through consulting, training, and investor readiness programmes, he helps founders create compelling investor pitches and secure funding with confidence.

  • Pre Seed Startup Pitch Deck: Funding Guide

    Pre Seed Startup Pitch Deck: Funding Guide

    Pre-Seed Startup Pitch Deck: Funding Guide

    James Church

    WRITEN BY

    James Church

    Author, Investable Entrepreneur

    James is an award-winning business advisor and best-selling author. His clients have raised over £200m in early-stage funding. 

    What should a pre-seed startup deck include?

    A strong pre seed startup pitch deck should explain the customer problem, proposed solution, target market, business model, early validation, founding team, funding request, and future milestones. Investors do not expect a fully established company at this stage, but they do expect clear thinking, credible evidence, and a practical plan for using early investment.

    The main purpose of the deck is to help investors understand the opportunity quickly. Every slide should communicate one important point and support the overall investment story.

    A useful deck structure includes:

    • Customer problem
    • Proposed solution
    • Target audience
    • Market opportunity
    • Product or service overview
    • Early validation
    • Business model
    • Go-to-market strategy
    • Competitor positioning
    • Founding team
    • Funding requirement
    • Planned use of funds
    • Future milestones

    .
    Founders should avoid overcrowding slides with lengthy paragraphs, complicated charts, or unnecessary technical details. Clear headlines, concise statements, relevant figures, and simple visuals usually make the presentation easier to understand.

    The problem slide should explain who experiences the issue, why it matters, and why current alternatives are not effective enough. The solution slide should then show how the startup addresses that problem in a practical and valuable way.

    How do investors assess an early-stage startup?

    Investors assess an early-stage startup by reviewing the quality of the problem, the founder’s understanding of the customer, the market opportunity, early evidence, and the team’s ability to execute. Since the business is still developing, investors focus on whether the founders can test assumptions, learn quickly, and make sensible decisions.

    Early validation can include:

    1. Customer interviews
    2. Prototype testing
    3. Waitlist registrations
    4. Letters of intent
    5. Pilot discussions
    6. Early users
    7. Initial revenue
    8. Customer feedback

    .
    The evidence does not need to involve thousands of users. A small number of detailed customer interviews may be more valuable than a large social media following that does not demonstrate genuine customer demand.

    The market section should also be realistic. Instead of relying only on a large global market figure, founders should identify their first customer segment, explain how they plan to reach that audience, and show how the business could expand over time.

    Investors also review the founding team carefully. At the pre-seed stage, they are often investing in the founders as much as the business idea.

    The team slide should explain why the founders are qualified to solve the problem. Relevant strengths may include industry experience, technical skills, customer relationships, previous business experience, or personal knowledge of the market.

    Why is timing important for a pre-seed startup?

    Investors also want to understand why the opportunity is relevant now. Changes in customer behaviour, technology, regulations, market conditions, or industry trends can create new opportunities for startups. A strong pre-seed deck should briefly explain what has changed and why the startup is well positioned to respond.

    Why does a pre-seed funding deck matter?

    A pre seed funding pitch deck matters because it helps founders organise their investment story before approaching potential investors. It connects the problem, solution, market, evidence, team, and funding plan in a format that is easy to review and discuss.

    A strong funding deck does more than describe the business. It should explain why the opportunity matters, why the timing is right, and what the startup can accomplish with additional capital.

    The funding request should clearly state:

    • How much capital is being raised
    • How the money will be used
    • Which milestones will be achieved
    • How long the investment may support the company
    • What evidence will be created before the next funding round

    .
    Common uses of pre-seed funding include product development, customer research, market testing, key hires, compliance, sales activity, and operational costs.

    The funding request should connect directly to measurable outcomes. For example, product investment may support the completion of a working prototype, while customer research may help validate pricing, demand, and the target audience.

    Financial projections should support this plan. Early forecasts do not need to predict the future perfectly, but they should explain expected revenue, costs, hiring requirements, and cash needs.

    Founders should avoid unrealistic projections that are not connected to a practical customer acquisition strategy. Investors usually value credible assumptions and a clear operating plan more than exaggerated numbers.

    What makes a pre-seed deck investor-ready?

    An investor-ready pre seed pitch deck presents a focused story, relevant evidence, realistic assumptions, and a specific funding request. It should help investors understand what has already been tested, what still needs to be proven, and how early investment will help reduce business risk.

    Before sharing the deck, founders should check that:

    • Every slide has one clear purpose
    • Market claims are supported by evidence
    • Customer validation is relevant
    • Competitors are acknowledged
    • The business model is easy to understand
    • Financial assumptions are realistic
    • The funding request is specific
    • Use of funds connects to milestones
    • The presentation sounds authentic

    .
    The final deck should reflect the founder’s voice. Investors want to hear a clear and credible explanation of the business, not generic wording that could describe any startup.

    Founders should also practise presenting the deck aloud. A slide may appear clear on screen but feel difficult to explain during a conversation. Rehearsing helps founders improve their delivery, identify unclear sections, and prepare for investor questions.

    A strong presentation will not guarantee investment, but it can improve the quality of investor conversations. It helps founders communicate the opportunity confidently and gives investors the information they need to decide whether they want to learn more.

    Frequently Asked Questions

    How many slides should a pre-seed deck have?

    Most pre-seed decks contain around 10 to 15 core slides. The exact number matters less than clear messaging, relevant evidence, and a logical investment story.

    Do pre-seed startups need revenue?

    No. Revenue can help, but customer interviews, prototypes, pilot programmes, waitlists, letters of intent, and early user feedback can also demonstrate meaningful validation.

    Should a pre-seed pitch deck address business risks?

    Yes. A strong deck should show that founders understand the key risks and assumptions behind the business. These may include customer demand, pricing, competition, technology, regulation, or customer acquisition. Explaining how the team plans to test and reduce these risks can demonstrate practical thinking and investor awareness.

    What is the main goal of a pre-seed pitch deck?

    The main goal is to earn the next investor conversation by explaining the opportunity, demonstrating team credibility, and showing how funding will support measurable business milestones.

    What is the difference between a pre-seed and seed pitch deck?

    A pre-seed deck usually focuses more on the problem, solution, market opportunity, founding team, early validation, and the assumptions that still need to be tested. A seed deck generally includes stronger evidence of product-market fit, traction, revenue, customer growth, and a more developed go-to-market strategy. The exact focus depends on the startup and its stage of development.

    About the Author

    James Church is an award-winning startup fundraising consultant and the Amazon best-selling author of Investable Entrepreneur. His clients have raised more than £200 million in startup funding. Through consulting, training, and investor readiness programmes, he helps founders create compelling investor pitches and secure funding with confidence.

    Tags: how to pitch to investors, investor pitch deck consultant, what do investors look for in a pitch, startup fundraising, investor presentation, pitch deck consultant UK

  • Why corporate execs struggle raising investment

    Why corporate execs struggle raising investment

    Why corporate execs struggle to raise investment

    James Church

    WRITEN BY

    James Church

    Author, Investable Entrepreneur

    James is an award-winning business advisor and best-selling author. His clients have raised over £200m in early-stage funding. 

    Six months ago, you were the person everyone trusted in the boardroom.

    You knew how to manage stakeholders, defend budgets, and navigate operational complexity. Your experience carried weight because it reduced uncertainty. That’s what senior corporate leadership rewards.

    Then you became a founder and suddenly none of that seemed to land with investors.

    You leave pitch meetings feeling like you explained everything clearly, yet investors seem unconvinced. The feedback is vague. “Interesting, but early.” “Not quite there yet.” “We’re not feeling enough conviction.”

    And this is where many first-time founders with corporate backgrounds become deeply confused, because they assume fundraising is a test of business rigour when in reality it is much more a test of founder belief.

    Over the last decade working with founders on fundraising, I’ve sat in calls with thousands of entrepreneurs. A pattern became impossible to ignore. Founders coming from corporate environments consistently pitched differently from founders who came from SMEs or more entrepreneurial backgrounds.

    Not necessarily worse founders. Often highly capable people. But they approached investors with the wrong operating system.

    Investors are not buying certainty

    Corporate environments condition people to minimise risk.

    That makes sense when you’re managing a division inside an established company. You’re accountable for budgets, predictability, process, and downside protection. Senior leaders are rewarded for demonstrating control. You learn to present ideas carefully. You caveat statements. You acknowledge risks before someone else does.

    That behaviour is rational inside large organisations. But it becomes a fundraising problem when carried into startup investing.

    Investors are not allocating next quarter’s operational budget. They’re making strategic bets on uncertain futures. They already know startups are risky. In many cases, they assume failure is most likely.

    So when founders spend most of a pitch trying to prove they’re “safe”, the presentation starts working against them.

    I see this constantly in decks from ex-corporate founders. The pitch becomes overly analytical. Slides become crowded with detail. The founder tries to explain every assumption, every caveat and every market nuance. The vision gets softened in an attempt to sound realistic.

    What they think sounds more credible just sounds hesitant. The trouble is that investors interpret excessive caution as lack of belief.

    The corporate instinct to defend instead of enrol

    One of the clearest differences I notice is that corporate executives are trained to defend decisions. Whereas founders need to enrol investors into the vision.

    In a corporate setting, if you overstate an opportunity and underdeliver, your credibility suffers. So you learn to moderate expectations, to present balanced arguments and seek to avoid sounding emotionally attached to an outcome.

    Fundraising requires almost the opposite energy. Not blind optimism, but conviction.

    The strongest founders I see are able to communicate a future outcome with unusual clarity. Instead of sounding like someone presenting a business case for approval, they sound like someone inviting investors into a future they are already committed to building.

    Conviction is not delusion

    This is where people often misunderstand the advice. Conviction does not mean pretending there is no risk.

    Experienced investors know exactly how difficult startups are. In fact, sophisticated investors will usually trust founders less if they appear naive about the challenges ahead.

    So while you present the big vision with conviction, you also need to build credibility around how you’ll get there. A logical plan backed by market evidence and an understanding of the financial upside relative to the risk involved. 

    This is where ex-corporate founders can have a real advantage. They often know their market inside out and have spotted something others are missing. This unique insight can be used as a superpower to demonstrate why you’re best positioned to make your idea a reality.

    Delusion is simply believing an idea will work because you want it to. Conviction on the other hand, is being able to explain why it should work despite the uncertainty. 

    Ultimately, investors are not evaluating whether your startup is risk-free. They’re calculating whether you are a risk worth taking.

    What investors are actually evaluating

    A surprising number of first-time founders assume investors are mostly assessing the idea. In practice, they’re heavily assessing the founder. 

    Every investor knows markets shift, products evolve, and business models change. Early-stage companies rarely execute exactly according to the original plan. So what investors are really trying to determine is whether the founder can navigate uncertainty better than other founders who are pitching for the same pot of cash.

    That’s why building credibility around the founders and their vision matters so much in early-stage investing. They’re looking at founder insight, market understanding, the ability to execute, evidence of traction, product-market alignment, defensibility and commercial awareness.

    But above all, they are trying to answer a simpler question:

    “Do I believe this person can turn this vision into reality?”

    That is a very different question from:

    “Has this person eliminated all possible risk?”

    Your pitch is not due diligence

    One of the simplest mindset shifts I encourage founders to make is this – your pitch deck is not the entire investment process. It is the beginning of a conversation.

    This sounds obvious, but many first-time founders behave as though the initial pitch meeting must answer every possible question upfront. They overload the deck with detail because they are trying to pre-empt objections before trust has even been established.

    Your pitch is the billboard, not the terms and conditions. Imagine if instead of an attention-grabbing headline and an engaging image that gets us curious about a product, global brands instead put the full product specification along with the complete t’s and c’s on their billboard. Engagement would tank; everyone would just walk past, oblivious that the product even existed.  

    This is essentially what you’re doing when you add more content to each slide to provide answers to all your pre-empted questions.

    The best pitches are confident, focused, and commercially clear. They enrol investors into the scale of the opportunity. They communicate the business model succinctly. They establish why this founder has earned the right to solve this problem. All the depth comes later.

    Serious investors will absolutely challenge assumptions, they will scrutinise the numbers and they will explore risk in detail. But that usually happens after they are already interested.

    The purpose of the pitch is not to prove you can’t fail. It’s to give investors enough confidence to take a meeting and explore things further.

    The founders who raise understand one thing

    The founders who raise capital well are rarely the ones trying hardest to sound impressive. They’re usually the ones who communicate the most compelling vision with the greatest clarity. They have a strong, single-minded conviction grounded in evidence, market understanding, execution capability, and commercial logic. But one they can express in a few words on a handful of slides.

    This positioning is especially important for corporate executives entering entrepreneurship for the first time. Their experience is often valuable, and their operational understanding can become a major advantage. But during fundraising, that same background can unintentionally suppress the very thing investors need to see most clearly – their conviction.

    And if you pitch like someone defending a budget instead of building an inevitable future, investors will usually respond accordingly.

  • How to create an investor pitch deck that actually raises money

    How to create an investor pitch deck that actually raises money

    How to create an investor pitch deck that actually raises money

    James Church

    WRITEN BY

    James Church

    Author, Investable Entrepreneur

    James is an award-winning business advisor and best-selling author. His clients have raised over £200m in early-stage funding. 

    Most founders spend weeks designing their investor pitch deck. They obsess over fonts, colour schemes, and slide order. They polish every word until it feels perfect. And then they walk into a room full of investors and wonder why the conversation never quite lands the way they expected.

    The problem is rarely the design. It is almost always the story. A great investor pitch deck is not a brochure for your business. It is a carefully constructed argument that answers the questions every investor is already asking before you even open your mouth. Get that argument right, and the slides almost do not matter. Get it wrong, and no amount of beautiful design will save you.

    I have reviewed hundreds of pitch decks over the years. The ones that raise money share the same fundamental qualities. The ones that don’t tend to make the same predictable mistakes. This article breaks down what separates the two.

    What is an investor pitch deck?

    An investor pitch deck is a presentation, typically between ten and fifteen slides, that a founder uses to communicate the investment opportunity to potential investors. It covers the problem being solved, the market opportunity, the business model, the traction achieved so far, the team behind it, and the financial ask.

    It is not a business plan. It is not a detailed financial model. It is the story of your business told in the most compelling and concise way possible, designed to get an investor interested enough to ask for a follow-up meeting.

    The best pitch deck examples are not the most complex ones. They are the clearest ones. Investors see dozens of decks every week. The founders who cut through the noise are those who make the opportunity impossible to ignore.

    Free Fundraising Workshop with best-selling author - James Church

    What every investor is really asking

    When an investor looks at your deck, they are not just evaluating the business idea. They are running through a mental checklist of questions. Your deck needs to answer all of them, whether you realise it or not.

    Is the problem real and painful enough that people will pay to have it solved? Is the market large enough to justify the investment? Does this team have what it takes to execute? Is there already evidence that customers want this? And finally, can I see a path that delivers a return on my investment?

    Every slide in your deck should answer at least one of those questions. If a slide does not serve that purpose, it should not be in the deck.

    The core structure of a strong pitch deck

    The structure of your investor pitch deck matters more than most founders appreciate. A strong opening hook is essential. Investors decide within the first two or three slides whether they want to keep reading. If those slides are vague or unclear, you have already lost them.

    Start with the problem. Not a generic observation about the industry, but a specific, vivid description of the pain your customer is experiencing right now. Make the investor feel that pain before you introduce your solution.

    Then introduce your solution clearly and simply. One sentence should be enough. If you cannot describe what your business does in a single clear sentence, that is a sign the proposition needs more work before you pitch.

    After that, build the case with your market size, traction, business model, team credentials, financials, and your ask. Each section should flow naturally into the next. Investors should feel they are following a logical journey, not jumping between disconnected facts.

    In my book, Investable Entrepreneur, I outline the five-act structure that I’ve developed and honed over many years. This structure ensures your investor pitch delivers content in a rhythm that keeps investors engaged. The result is decks that achieve a 6x higher engagement rate. 

    Startup Fundraising Success

    The most common pitch deck mistakes

    Looking at pitch deck examples from founders who have raised successfully versus those who have not, the same mistakes appear time and again on the unsuccessful side.

    The first is burying the business model. Investors need to understand how you make money early in the deck. If they get towards the end and are still unclear on the revenue model, they will have already mentally moved on.

    The second is weak or missing traction. Even at the pre-seed stage, investors want to see evidence that the market wants what you are building. A waitlist of five hundred people, a letter of intent from a major client, or three months of consistent revenue growth tells a more powerful story than any slide about your addressable market.

    The third is an unclear ask. Many founders present a beautifully crafted deck and then end with a vague statement about raising capital. Investors want to know exactly how much you are raising, what you will use it for, and what milestones that funding will allow you to hit.

    What a great pitch deck example looks like in practice

    One founder I worked with had a strong product but a deck that was full of industry jargon and technical detail. Investors were struggling to connect with the opportunity. We stripped it back entirely. The problem slide became a single sentence describing the exact moment a customer felt the pain. The solution slide became one clear line. The traction slide showed three compelling data points rather than twelve.

    Startup Pitch Deck

    The result was a deck that investors could understand in sixty seconds and feel confident enough in to ask for a meeting. That is the standard to aim for. Not beautiful. Not clever. Clear.

    When to get professional help with your deck

    If you have pitched more than five times without getting to a second meeting, the deck is almost certainly part of the problem. Many founders wait too long before seeking outside perspective. They are too close to their own business to see where the story breaks down.

    Working with an experienced pitch deck consultant gives you the outside view that is almost impossible to give yourself. A good consultant will challenge your assumptions, tighten your narrative, and ensure your deck answers the questions investors are asking rather than the questions you wish they were asking.

    The most successful rounds I have been involved with were not the ones where the founder had the best idea. They were the ones where the founder told the clearest story. That clarity starts with getting your investor pitch deck right before you walk into a single meeting.

    If you are preparing to raise and want to make sure your deck is genuinely investor-ready, explore my pitch deck consulting services and take the first step towards a fundraise that works.

  • Your pitch deck doesn’t need more AI. It needs more of you.​

    Your pitch deck doesn’t need more AI. It needs more of you.​

    Your pitch deck doesn’t need more AI. It needs more of you.

    James Church

    WRITEN BY

    James Church

    Author, Investable Entrepreneur

    James is an award-winning business advisor and best-selling author. His clients have raised over £200m in early-stage funding. 

    There’s a big problem in the way founders are using AI for fundraising.

    Sure, the tools are getting better. They’re faster, more capable and able to produce something that seems highly polished in seconds. Yet the more founders use AI to build their decks, the more every deck starts to sound the same.

    Yes, the language is cleaner, the formatting is neater and the phrasing sounds more “investor-ready”, but somehow the result is far less persuasive.

    That’s because in a world of automation, cut-through now comes from humanisation.

    If you’re raising seed investment this really matters, probably more than you realise. Investors aren’t backing a sequence of well-constructed prompts. They’re backing a person. More specifically, they’re backing you. They’re backing your judgement, your clarity, your instinct and your ability to roll with the punches.

    AI can help you do the mundane work. It can speed up research, process information and reduce hours of manual effort. I use it heavily myself. I have trained custom GPTs to support parts of my work because it’s a powerful tool. But there’s a line. And that line is being crossed by too many founders. They’re not using AI for leverage, but to replace their critical thinking. And that’s where the problem starts.

    The autopilot mistake

    The way we use AI is much like flying a plane on autopilot.

    Autopilot, when launched, was a transformational technology. It handled all the routine parts of a flight, and it can make the process of flying safer and more efficient. But you still need a human for the most valuable parts – the take-off and the landing. Those are the moments that matter most. Those are the moments when judgement and experience come into play.

    Fundraising works the same way.

    If you run your entire fundraising process on autopilot, using AI to generate the story, shape the strategy and write the words, you remove the very thing investors are trying to assess. You. They want to know whether you can think clearly, whether you understand your market properly and whether your strategy is real or just well-presented.

    They’re investing in the pilot, not the automation.

    Too many founders are trying to use AI to cover up their gaps. They’re unsure what investors want to see or are not confident in how to communicate their business. So they ask ChatGPT or Claude to do the thinking for them. And the output always looks great, and it usually sounds credible at first glance. And that is the massive trap. It sounds so plausible that founders bank on it, and that works right up until someone asks a follow-up question.

    Then it all comes unstuck.

    Why this becomes obvious so quickly

    A lot of the founders I work with are building AI products themselves, so it’s completely natural that they turn to AI to help build out their investment memo, financials and pitch materials. It’s usually their first instinct.

    But as soon as I ask a question to explore deeper, I often get an AI-generated answer back. Straight away, you can tell they’ve not really thought it through. Instead, they’ve thought, “I’m not sure, I’ll get AI answer that for me.”

    So as soon as I ask these sorts of questions in a live conversation, they get found out, they can’t hide behind the output anymore. As a result, they fail to articulate what they meant. They can’t explain the reasoning behind the information they shared, and they can’t defend their assumptions. What looked polished in the deck falls apart because there’s no depth behind it.

    That’s what over-leveraging AI does. It erodes critical thinking. Founders all become a homogenous group sharing the same tactics and strategies articulated in the same robotic tone.

    The trouble is, AI is trained on what is broadly available. It triangulates all the data points to form an “opinion” on what is right. And this includes an enormous amount of advice, decks, articles and templates. The same advice that the 99% of founders who fail to raise funding have been consuming via blog posts and accelerator programmes for the past decade or more.

    And this really matters because the goal of pitching is not to make you look like the average founder – the 99% who fail. The goal is to make you look like the top 1% who succeed.

    When AI fails to distinguish between the mass advice that’s been guiding founders to raise unsuccessfully for years, and the tiny amount of advice that genuinely helps founders raise, you end up in a position where founders who should be positioning themselves as a 1 in a 1,000 generational talent are putting blind faith in a robot who relies on the law of averages.

    When you use it carelessly, AI just pulls you towards the middle. In fundraising, the middle is where most visions die.

    If AI was the answer, fundraising success would be rising

    This is a question I think more founders should consider…

    If AI was genuinely better than a human at helping you connect with an investor and persuade them to part with their capital, why are founders still struggling so much to raise?

    Why are we not seeing a dramatic increase in success rates now that so many people have access to these tools?

    The fact is, we’re not seeing that.

    You can argue, rightly, that market conditions are tougher now than they were five years ago. That is true. But if AI was fundamentally changing the quality of founder communication, there should still be some obvious lift in success rates.

    But there isn’t, because founders aren’t leveraging it in the way they should be.

    It’s making decks more uniform. It’s reproducing the same stale thinking and it’s turning a founder’s passion into something corporate, robotic and less memorable.

    For me, this is exactly why humanisation is now the advantage.

    How to use AI without losing your edge

    I am not arguing that you should avoid AI. I’m arguing that you should use it properly.

    Of course, you should use it in preparing your round where it genuinely creates leverage. Things like processing customer interview transcripts, spotting patterns in data, and uncovering hard-to-find desk research are all great use cases. This cuts manual work that would otherwise take hours or weeks. In some cases, it identifies patterns you’d never had spotted. This is where AI is at its strongest. And this can give you incredible insights you can use to build your credibility with investors and give you a real edge.

    But when it comes to your deck, the right way to use AI is to start with depth, not shortcuts.

    When creating content, us humans rarely achieve the best articulation of a concept immediately. Ask any advertising executive. They’ll tell you the brochure is much easier to write than the billboard. Distilling the message down to its core takes a process of distilling information.

    You need to guide any AI you use through that process. Doing so allows the AI to act more closely to the human mind.

    Step 1: Do the hard yards

    Before you even think about slide design or tidy bullet points, map your pitch like a business plan.

    For each slide, write at least 500 words explaining what is strategically important. Do the messy thinking yourself. Explain the problem fully. Explain the solution fully. Write out your reasoning, your traction, your roadmap, your go-to-market approach.

    This is the work most founders try to skip, and it’s the work that creates the substance investors are actually looking for.

    Step 2: Use AI to distil the core points

    Once you’ve laid down your strategic thinking, use AI to distil the information (I find Chat GPT is best for this). Feed in those long-form sections and ask it to pull out the most relevant points as single-line bullets using the below prompt. That gives you a launch pad for slide content.

    You are a pre-seed / seed investment consultant with deep experience in the [country] funding landscape. I will shortly upload notes about key sections of my business model that are most relevant to an investor pitch, which you will use as the basis of the output. With the notes provided, produce a concise bullet point list distilling the content into a list of 6-12 word bullet points. You should consider the key elements that are most relevant and impactful with investors. Reduce the content down to a maximum of 10 bullet points. Keep it plain English. Reflect the inputs faithfully, without contradicting or replacing their core concept. Do not invent new information; keep strictly to the information provided.

    This way, you’re going from your deep strategic thinking to condensed clarity. Rather than surface-level thoughts to polished garbage.

    Step 3: Write your deck

    Use the distilled points to create the first draft of your deck by yourself. Use the most compelling and impactful point as your headline. This hooks the reader. Select other points to form the core content of your pitch deck. But be selective. Your goal is to engage, not educate. So, only select the information that you believe will lead the investor to want to take the conversation further with you.

    Step 4: Refine with AI
    Take your deck back into an AI tool (I find Claude is best for this). Start with the following prompt, then feed in the draft content of your deck.

    You're my copywriting assistant. I'm going to share with you some draft slide content for an investor pitch deck. I need you to enhance the content by making it shorter, punchier and more memorable where possible. The tone should be bold, disruptive and credible. All slides need to elevate the value proposition and make the product and opportunity sound exciting to Angels and VCs. We're aiming for slides of 50-75 words a slide. Please do not repeat the same headline structure too often. The output should match the text structure of the input. For example, if the input is bullet points, the output should also be bullet points. Avoid headlines that use the rule of three. Ensure all headlines act as a summary of the slide, allowing investors to quickly understand the key takeaway for each slide.

    The output will not have nailed it. The correct slide is probably somewhere between the Claude output and your original. Strategically select the improvements and keep the content you wrote that you think is better.

    WARNING: When following this process, you’ll need to be wary of the language trap. AI loves financial buzzwords. It writes as though every investor is an institutional VP reading a board memo. But most pre-seed and seed investors are founders and entrepreneurs themselves. In many cases, the best way to explain your business is the way you would explain it to a mate down the pub.

    The real problem for founders

    Founders are under pressure. There is so much to do and not enough time to do it. You’re expected to move quickly, cover every role and somehow still show up as strategic, thoughtful and investor-ready. So, of course, you look for shortcuts.

    You should be looking for shortcuts in manual processes, ways to streamline anything repetitive and systems that can automate junior tasks.

    But fundraising is not a junior task.

    At its core, fundraising is human. It’s one person trying to get another person excited enough to believe and trust in their idea. That means your job isn’t just to assemble information, it’s to enrol investors into your vision. Only a human can do that properly.

    A lot of founders use AI because, underneath it all, they’re simply unsure. They don’t fully know what investors are looking for. They don’t trust their own instinct enough. And with all of the world’s knowledge available at the click of a button and presented as customised to you and your business, it’s clear to see why you might think AI will somehow do a better job of sounding investable.

    But more often than not, it just strips out the one thing that would have made your pitch compelling in the first place – you.

    That’s why I think more founders need to break free of the idea that AI can improve the essence of their pitch. It can improve the processing and the efficiency. But it can’t improve the human core unless that core is already there.

    What I would do next if I were in your position

    Take your current deck slide by slide and force yourself back into the substance.

    Follow the process outlined above. Do the hard yards and then use AI to help you boil it down. Write the pitch deck yourself without AI assistance and then leverage AI to sharpen where needed.

    That process is slower than prompting a tool to write ten slides for you in 5 seconds. But it’s also far more likely to produce something worth backing.

    The founders who stand out now aren’t the ones using the most AI. They’re the ones using it with restraint. They let it handle the automation while they hold on to the human connection. And in pre-seed and seed stage fundraising, the human connection is the thing that matters most.

  • Investors decide in 4 seconds, long before they read your pitch

    Investors decide in 4 seconds, long before they read your pitch

    Investors decide in 4 seconds, long before they read your pitch

    James Church

    WRITEN BY

    James Church

    Author, Investable Entrepreneur

    James is an award-winning business advisor and best-selling author. His clients have raised over £200m in early-stage funding. 

    Most founders believe investors evaluate startups by analysing the business case. But the decision about how seriously to take your company often happens long before that process even begins.

    It happens the moment they open your pitch deck.

    Within roughly four seconds, investors form an impression about the quality of your opportunity – before they read your numbers, before they examine your strategy, and before they understand your product. This first impression quietly shapes everything that follows.

    This feels unfair, but it’s perfectly human. And once you understand it, it becomes something you can use to your advantage.

    Investors don’t start with analysis. They start with signals.

    There is a persistent belief in early-stage fundraising that investors approach decks like technical documents. Founders assume evaluation begins with market size, traction or financial logic.

    It rarely does. The first judgment investors make is whether what’s in front of them feels credible and worth their time looking into further. And this happens subconsciously.

    The design of your pitch deck is the first evidence investors receive about how you think, how you execute and how seriously you take your own company. Before they read a single sentence, they are already forming expectations about what kind of founder they are dealing with.

    If the deck feels considered and intentional, investors relax into the material. If it feels rushed, they become cautious. This first impression affects how every slide is interpreted afterwards.

    Four seconds is enough to change the trajectory of a conversation

    Investors regularly review large volumes of material under time pressure. They don’t deeply analyse every opportunity at first contact; it’s human nature to rely on early signals to decide where to invest attention.

    The design of your deck becomes one of those signals.

    We’re told not to judge a book by its cover. Why? Because we’re always doing exactly that. We know we shouldn’t, but we can’t help it, it’s how we’re programmed. 

    A strong visual presentation communicates something immediate. It tells investors that this company is organised, that the founder understands positioning, and that they care how they are perceived externally. All great traits in someone you’ll be investing in.

    A weak presentation communicates something else entirely. It tells investors that execution may be inconsistent, the founders’ thinking may be unclear and that this opportunity may not be ready yet.

    None of this assessment requires a single word to be read.

    And once that impression forms, it stays in the background while the investor continues through the deck. If they even bother.

    Visual judgement happens faster than rational judgement

    Humans process visual information around 6,000 times faster than written content. Investors are no exception. When they open your pitch deck, they’re not consciously scoring typography or layout. But they are responding instinctively to hierarchy, structure and clarity.

    A good pitch design signals capability, care and ambition. Poor design introduces friction. It makes investors work harder to understand what they are seeing, and that effort subconsciously shifts their confidence in you and your opportunity.

    Founders sometimes assume investors can separate presentation from substance. In reality, presentation shapes how substance is perceived.

    A pitch deck is not just communication. It is evidence.

    One of the most overlooked realities in fundraising is that investors rarely evaluate only what founders say. They also evaluate what founders demonstrate.

    Your pitch deck demonstrates how clearly you can structure information and how well you can grab attention – all key traits of a founder who wants your money to start marketing their product to the masses. 

    If a founder has invested effort into presenting the opportunity well, investors often assume similar discipline exists inside the business – not just in marketing, but at all levels.

    But if that effort appears absent, a different question appears. Investors start to wonder the state of things behind the scenes. This self-inflicted doubt often determines whether the conversation continues at all.


    This isn’t about aesthetics. It’s about credibility

    Some founders resist the idea that presentation quality affects investment outcomes. They prefer to believe strong businesses speak for themselves.

    And of course, strong businesses do speak for themselves. But only after investors decide to listen. The quality of your presentation does not replace strategy, traction or clarity of thinking. But it does create the conditions in which those strengths can be recognised.

    Investors are making decisions under immense uncertainty. So they rely on signals (a gut feeling) to help them decide if it’s worth their time. A considered deck doesn’t replace the fundamentals, but it does make the fundamentals visible.

    If investors decide how seriously to take your company within seconds of opening your deck, then those seconds deserve more attention than most founders currently give them.

  • Investor Readiness Explained: Why some founders get funded and others don’t

    Investor Readiness Explained: Why some founders get funded and others don’t

    Investor Readiness Explained: Why some founders get funded and others don’t

    James Church

    WRITEN BY

    James Church

    Author, Investable Entrepreneur

    James is an award-winning business advisor and best-selling author. His clients have raised over £200m in early-stage funding. 

    I often hear founders say they’re “ready to raise”. What they usually mean is they’re low on cash or excited about what they’ve built. None of those things make a business investor-ready.

    Investor readiness isn’t a mindset or a milestone. It’s a signal. And whether you intend it or not, you’re sending that signal the moment an investor looks at your materials.

    I see this play out repeatedly in accelerators, incubators and founder communities. Two companies can look almost identical on the surface – same market, same stage, even similar traction. One walks away funded, the other doesn’t.

    The difference is rarely the idea, and nearly always about how clearly the founder demonstrates they can be trusted with capital.

    Why “great ideas” get ignored

    There’s a persistent belief that investors fund the best innovations. That belief causes a lot of frustration when founders see less impressive businesses close rounds while they struggle.

    In practice, investors don’t fund ideas. They fund risk-adjusted returns.

    That distinction matters. Investors are making decisions under uncertainty, and so they rely on signals to reduce that uncertainty. If those signals aren’t there, enthusiasm for the idea doesn’t compensate.

    This is where many founders misunderstand what investors look for. They focus on explaining the product, the technology, or the market size, without proving that they understand the mechanics of building a commercial business around it.

    Investor readiness isn’t about being impressive. It’s about being believed.

    The three signals behind investor readiness

    When an investor reviews a pitch, a financial model or a business plan, they’re subconsciously asking the same questions every time.

    Can this founder be resourceful when things don’t go to plan?

    Do they understand the financial risks as well as the upside?

    Do they know how this business actually turns into commercial success?

    Founders who close rounds consistently answer those questions without needing to say them out loud.

    Those signals appear across three critical fundraising materials – the pitch, the projections, and the investment memo.

    1. The pitch signals resourcefulness

    A pitch isn’t there to prove intelligence. It’s there to sell a vision that other people want to support.

    When an investor buys into the vision, they assume the founder can also attract future capital, convince top talent, and build credibility with partners and advisors. If the investor is excited by the founders’ pitch, there is no reason to think these other stakeholders would be too.

    This builds instant trust in a founder’s ability to unlock the resources needed to succeed.

    A confused or overly technical pitch does the opposite. It signals that the founder may struggle to mobilise people around the business, even if the idea itself is strong.

    Investor readiness shows up when the pitch is clear, intentional, and designed around the investor’s decision-making process – not the founder’s need to explain everything they know.

    2. Financial projections signal risk awareness

    Investor-ready financial projections are often treated as a necessary evil. Something founders rush through because they assume no one believes the numbers anyway.

    That’s a mistake. Investors aren’t looking for precision – they’re looking for understanding.

    A coherent P&L, cash flow, balance sheet, and supporting metrics demonstrate that the founder understands where the business is exposed, how cash moves through the company, and what needs to go right for returns to materialise.

    This is the difference between optimism and investment readiness. Founders who acknowledge financial risk signal credibility, while the founders who avoid it raise huge red flags.

    3. The investment memo signals commercial execution

    The investment memo is essentially a top-level business plan for investors.

    During due dilligence investors want to see that there is a clear implementation strategy behind the vision. They want clarity that you understand how the business moves from today’s reality to tomorrow’s returns.

    This is where many founders fall into abstract language. Big markets, strong demand, scalable models. None of that explains how the company actually executes.

    A credible plan shows that the founder understands the sequence of decisions, trade-offs, and constraints involved in building commercial success. It signals that growth is engineered and not just hoped for.

    Why charisma doesn’t make you investor-ready

    Some founders assume that those who raise easily are just better performers. They’re better at public speaking and just more confident under scrutiny.

    Of course, confidence helps – but it’s often not what gets deals done.

    What closes rounds is consistency. When the pitch, the projections and the investment memo all reinforce the same strategic narrative, investors don’t have to work hard to believe the business is real and the founder is capable.

    That’s what true investment readiness looks like. Not bravado, but alignment.

    “I’ll fix this after I raise” is the wrong order

    A common objection I hear is that founders will tighten their numbers or refine their strategy once funding is secured. They want money for the idea, and will do the thinking later. From an investor’s perspective, that logic works in reverse.

    If a founder hasn’t demonstrated control over their business before taking money, there’s little reason to believe they’ll suddenly develop it afterwards. Capital amplifies existing actions and behaviours; it doesn’t suddenly create them.

    Essentially, investor readiness is all about earning trust before asking for it.

    The investor-ready signal you’re really sending

    Every fundraising conversation sends a message. Not just about the opportunity, but about the founder.

    With an articulate pitch, credible financials and a believable strategy, you’re signalling that you understand what it takes to turn capital into returns.

    Without them, you may still have a great idea – but you don’t yet look like a safe pair of hands.

    That distinction explains why some founders raise again and again, while others stay stuck wondering why investors “didn’t get it”.

    So instead of asking whether investors will like your idea, ask yourself something more useful:

    Have I made it easy for an investor to say yes?

    Investor readiness isn’t about persuasion. It’s about preparation. And the founders who treat it that way stop competing on passion and start competing on trust.

    If you want to raise funding, success begins with preparation, not the pitch.

  • How early-stage investors evaluate your startup​

    How early-stage investors evaluate your startup​

    How early-stage investors evaluate your startup

    James Church

    WRITEN BY

    James Church

    Author, Investable Entrepreneur

    James is an award-winning business advisor and best-selling author. His clients have raised over £200m in early-stage funding. 

    If you’re a founder raising capital, chances are you’ve spent hours – maybe days – obsessing over your pitch deck. Which slides should be in there, what order they should be in, what other decks look like…

    That’s understandable. There’s a lot of content out there telling you what a pitch should look like.

    But here’s the problem. Very little of that content explains how investors actually analyse an investment opportunity. And that gap causes a lot of founders to do the wrong thing. They complete the slides on the list, but they don’t put the information in those slides that actually moves the dial.

    So I want to break this down properly. Not from a “what slides do I need” perspective, but from the way investors really think when they’re assessing whether to back your business.

    Across pre-seed, seed and Series A, I see the same patterns again and again. Different funds, different cheques, but very similar thinking. In practice, investors are trying to understand eight core areas when they look at your opportunity.

    Once you understand those eight areas, the way you talk about your business – and the way you write your deck – changes completely.

    1. Investors start with you

    The first thing investors look for isn’t your market size or your product. It’s you.

    They’re asking a very simple question – is this a founder, or founding team, that can take an idea and turn it into something real. And then turn that reality into a scalable business that delivers returns.

    That second part matters just as much as the first.

    A great business is always a combination of two things. A strong idea in a scalable market, and a founder who can execute. Investors are looking for evidence that you can do both.

    Where founders go wrong is treating the team slide like an afterthought. It’s often right at the end of the deck, tucked away, with a few CV bullet points and some past job titles. That doesn’t tell an investor what they actually need to know.

    What they want to see is credibility. Authority. Signals that you can be trusted to build this venture.

    If you’ve built a track record, have deep industry experience, or have done something relevant before, bring that forward. Literally. Put the team earlier in the deck and frame the pitch as “this opportunity, brought to you by this team”.

    That one shift completely changes the context. The same information lands very differently when investors believe in the founder delivering it.

    2. Traction = Progress

    The second thing investors look for is traction. And traction doesn’t always mean revenue. What they really care about is progress. Evidence that the market wants what you’re building.

    Too many founders rely on third-party reports or generic market research. That’s not enough in today’s landscape. Investors want to see primary evidence – conversations you’ve had, experiments you’ve run, signals you’ve created.

    Revenue is great, but it’s not the only option. Early pilots, waiting lists, usage data, signed LOIs, repeat behaviour. All of that counts.

    Traction is proof that you can take an idea and move it forward. That you can turn thinking into action. It reinforces the belief that you’re capable of executing, not just presenting.

    This evidence should run through the deck. Dropping these key investability signals throughout the deck confirms to investors that this project is picking up serious momentum.

    3. Market size is only half the story

    Yes, investors want big markets. But size alone isn’t enough.

    What they’re really looking for is momentum. A market that’s big and ready for something new to happen.

    When you talk about your market, don’t just describe how large it is. Explain why now is the right time. What’s changing? What’s broken? What pressure is building that creates an opportunity for disruption?

    A huge market with no urgency is far less interesting than a slightly smaller market with real movement behind it.

    Consider the behavioural, legal, political and societal changes that are driving momentum, change and transformation in your market. 

    4. A simple, sharp proposition

    At the heart of every pitch is the value proposition. What problem are you solving, and why should anyone care?

    This is where founders often overcomplicate things. Too many features. Too much explanation. Not enough clarity.

    Investors want a top-level answer. What’s the problem? What’s the solution? Why does it matter to your customer? What transformation will it deliver?

    If you can’t explain that simply, in a handful of words, it’s a red flag – not because the idea is bad, but because it suggests a lack of focus. Clarity suggests confidence. Founders who overexplain come across as less confident in what they are building than those who have nailed their communication. 

    In advertising, the billboard headline is the most difficult thing to create. You have to distil everything into a handful of words. The confidence to talk about your incredible product with just a few words convinces audiences to buy a product. 

    The same is true with your value proposition. Your ability to boil down the essence of what you’re building to its core value proposition tells investors you’re ready to take this to market. 

    5. Competition = Positioning

    Every market has competition. Pretending otherwise doesn’t help you. What most investors hate are those comparison tables full of ticks for you and crosses for everyone else. They don’t believe them, and they don’t learn anything from them.

    In fact, when founders put their startup against global leaders, most investors don’t think “oh wow, they are doing something different than the big guys”, they think “these corporates have million-dollar R&D budgets to explore exactly what you’re building, and decided it’s not worth it”.  

    So be honest. Show where competitors are strong. Show where you’re weaker. Then explain how you position yourself differently. Most unicorns didn’t win because they had the best product. They won because they were the best at taking it to market. Differentiation in the eyes of the customer is what matters. 

    So focus less on features and more on how you differentiate in your market. A positioning map often tells that story far better than a feature checklist.

    6. Forecasts are a conversation starter

    Your financial projections are not a crystal ball, and investors know that. They’re not looking for a perfectly accurate forecast. What they’re looking for is a document that opens a sensible conversation about unit economics and strategy.

    Do the numbers show a believable growth trajectory? Do the margins make sense? Are you spending enough to achieve the growth you’re claiming you can achieve?

    One of the biggest red flags is expecting huge growth while barely spending anything to get there – it suggests the model hasn’t really been thought through. Or spending too much too soon – putting a large financial risk into the business before the model is fully proven. 

    Your forecast should align with what investors would reasonably expect for a business like yours, in a market like yours and at the stage you are at. Don’t re-invent the wheel; align your numbers with best-in-class startups with similar business models. It gives your numbers defensibility in the conversations that follow you submitting your spreadsheet. 

    7. The deal has to stack up

    No matter how exciting the idea, the deal still has to work. Investors need to see that the amount you’re raising, the equity you’re offering, and the valuation you’re proposing sit within a realistic range.

    If you’re miles away from what the market considers reasonable, the conversation ends quickly. As a rough benchmark, data from SeedLegals across around £1bn of deals shows that roughly 15% equity is sold in the first three rounds on average. In practice, that often looks more like 20% at pre-seed, 15% at seed, and 10% at Series A. This reflects risk and dilution over time. 

    Being open to meaningful equity at an early stage signals that you understand the risk your early investors are taking – and that you want to build collaboratively, not keep as much to yourself as possible from day one. Your ask reflects your attitude and your business culture. 

    8. Exit is a mindset

    Finally, there’s exit. You don’t always need a dedicated exit slide, but you do need to understand exit potential. Without an exit, investors don’t get their money back. That’s the reality. 

    The most useful thing you can do is study M&A activity in your sector. Who’s acquiring? What are they buying? And what did those businesses look like at the point of acquisition? 

    If you understand what a successful exit looks like in your market (i.e revenue levels, customer base, IP, strategic fit), you can reverse-engineer your roadmap to buy an acquirable business. That leads to much stronger conversations with investors when due diligence begins.

    Change how you pitch by understanding how investors think

    Once you really understand these eight areas, pitching stops being about filling in slides from a “what slides do I need in a pitch deck” ChatGPT prompt, and starts being about creating communication to sell your investment to investors.

    You’re no longer guessing what investors want to hear. You’re speaking their language, addressing their concerns, and showing that you understand how this game is actually played.

    That alone puts you ahead of most founders in the room.